- (+84) 86 696 0800
- htdn@tpm.com.vn
- 102 Phung Van Cung Street, Cau Kieu Ward, Ho Chi Minh City

- (+84) 86 696 0800
- htdn@tpm.com.vn
- 102 Phung Van Cung Street, Cau Kieu Ward, Ho Chi Minh City
Archives
- October 2026
- September 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- January 2024
- November 2023
Categories
Expanding Authority for Tax Refund Decisions: A New Step in Tax Administrative Reform
-
Vietnam Achieves Investment-Grade Credit Rating For The First Time From R&I
-
International Institutions Raise Positive Outlook For Vietnam’s Economic Growth In 2026
-
Ready-Built Factories Outpace Industrial Land, Attracting More Than USD 7 Billion In New Manufacturing FDI To Vietnam
-
German Businesses Accelerate Investment In Vietnam’s Green Hydrogen Sector
-
First Eight Months Of 2026: FDI Inflows Into Vietnam Surpass USD 40 Billion
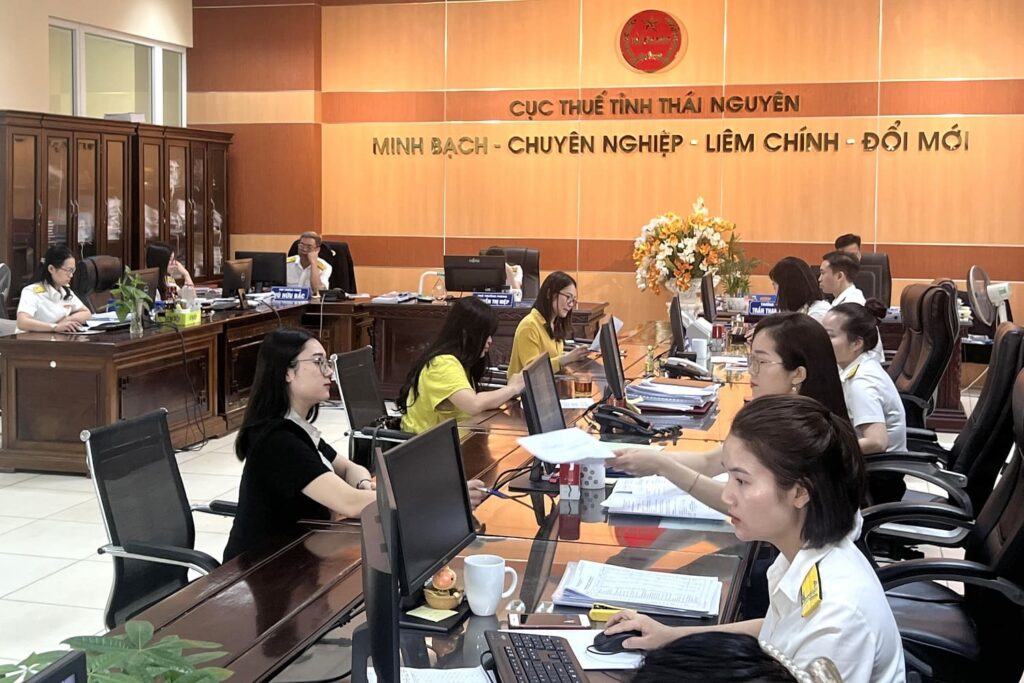
To address challenges in the tax refund process and create a more favorable business environment, the Ministry of Finance has recently proposed granting additional authority to decide on tax refunds to lower-level tax management agencies. This proposal is expected to shorten refund times, enhance the effectiveness and efficiency of tax management, and foster a more conducive business environment.
Cause of the Problem
Current tax management laws stipulate that only directors of provincial or centrally-affiliated city tax departments have the authority to approve tax refunds. This has led to several drawbacks:
- Prolonged refund times: Large enterprises must submit refund applications to higher-level authorities, causing delays and affecting their cash flow.
- Cumbersome administrative procedures: The process involves excessive administrative procedures, creating difficulties for businesses.
- Underutilization of resources at lower levels: Lower-level tax management agencies, which have direct contact with businesses, lack the authority to make decisions, resulting in resource waste.
Proposed Solution
To overcome these limitations, the Ministry of Finance has proposed granting refund approval authority to directors of large enterprise tax departments, as well as heads of tax sub-departments and regional tax sub-departments. This means:
- Large enterprise tax departments: Will have the authority to approve refunds for large enterprises under their management.
- Tax sub-department heads: Will have the authority to approve refunds for businesses under their jurisdiction.
Benefits of Expanding Authority
Expanding refund approval authority offers numerous benefits:
- Shorter refund times: Businesses will receive refunds more promptly, improving cash flow and enhancing investment capacity.
- Reduced administrative procedures: Unnecessary procedures will be eliminated, creating a more business-friendly environment.
- Improved tax management efficiency: Maximizing the use of resources at all levels of tax management, fostering proactivity and accountability.
- A more conducive business environment: Attracting investment and stimulating economic growth.
Business Feedback
The business community has expressed strong support for the Ministry of Finance’s proposed amendments. Expanding refund approval authority is seen as a significant step forward in administrative reform, creating a more favorable business environment.
Conclusion
Granting additional authority to decide on tax refunds is an effective solution for improving the business environment and facilitating business development. It is also part of the ongoing administrative reform and modernization of Vietnam’s tax management system.
-
Tax registration and tax declaration for individual business (“IB”) selling goods via Shopee in Vietnam
-
Newest Regional Minimum Wage In 2025
-
Trade Agreements (CPTPP, EVFTA, RCEP) Impact On FDI Enterprises
-
From July 1, 2025: Non-Salaried Business Managers Required To Participate In Mandatory Social Insurance
-
Property Rental Tax Obligations: New Regulations, Declaration & Updated Rates 2025-2026


TPM is proud to be an agency that provides full and excellent services in accounting, tax, HR & advisory services in Vietnam in nowadays business finance market.
Contact Us
TPM TAX AGENCY & CONSULTING CORPORATION
Tax Number: 0312787706
Feel free to contact & reach us!
Address: 102 Phung Van Cung Street, Cau Kieu Ward, Ho Chi Minh City
Email : htdn@tpm.com.vn
Hotline : (+84) 86 696 0800