- (+84) 86 696 0800
- htdn@tpm.com.vn
- 102 Phung Van Cung Street, Cau Kieu Ward, Ho Chi Minh City

1. Are charitable expenditures deductible?
Pursuant to Article 4 of Circular 96/2015/TT-BTC dated June 22, 2015 of the Ministry of Finance amending and supplementing Article 6 of Circular No. 78/2014/TT-BTC (amended and supplemented in Clause 2, Article 6 of Circular No. 119/2014/TT-BTC and Article 1 of Circular No. 151/2014/TT-BTC) as follows:
“Article 6. Deductible and non-deductible expenses when determining taxable income:
1. Except for non-deductible expenses stated in Clause 2 of this Article, enterprises are allowed to deduct all expenses if they meet the following conditions:
a) Actual expenses arising in relation to the production and business activities of the enterprise.
b) Expenses with sufficient legal invoices and documents as prescribed by law
c) Expenses with invoices for purchasing goods and services each time with a value of 20 million VND or more (prices including VAT) must have non-cash payment documents when paying
…2. Expenses that are not deductible when determining taxable income include:
…2.24. Expenses for funding disaster recovery not for the right subjects specified in Section a of this point or without records identifying the funding specified in Section b below…
2.25. Expenses for funding the construction of houses for the poor not for the right subjects specified in Section a of this point; Expenses for funding the construction of houses for the poor, houses for the poor, and houses of great solidarity as prescribed by law without records identifying the funding specified in Section b below:..
2.26. Expenses for funding scientific research not in accordance with regulations; expenses for funding policy beneficiaries not in accordance with regulations of law; Non-program funding expenditures of the State for localities in areas with particularly difficult socio-economic conditions…
2.32. Expenditures to support localities; expenditures to support unions and social organizations; Charity expenses (except for expenses for funding education, healthcare, overcoming the consequences of natural disasters, building houses of gratitude, building houses for the poor, building houses of great solidarity; funding scientific research, funding for policy beneficiaries as prescribed by law, funding under the State’s program for localities in areas with particularly difficult socio-economic conditions as stated in Points 2.22, 2.23, 2.24, 2.25, 2.26, Clause 2 of this Article)…”
Based on Official Dispatch 31943/CTHN-TTHT in 2022 on deductible expenses for charity expenses issued by the Hanoi Tax Department, the following instructions are provided:
- For expenses for funding education, healthcare, overcoming the consequences of natural disasters, building houses of gratitude, building houses for the poor, building houses of great solidarity; funding for scientific research, funding for policy beneficiaries as prescribed by law, funding under the State’s program for localities in areas with particularly difficult socio-economic conditions through agencies and organizations with the function of mobilizing funding as prescribed by law, the Company is allowed to account for deductible expenses when determining taxable income for corporate income tax if the expenditure is for the right subjects and there are sufficient documents to determine the funding amount as prescribed in Section a, Section b, Points 2.22, 2.23, 2.24, 2.25, 2.26, Clause 2, Article 6 of Circular 78/2014/TT-BTC (amended and supplemented in Article 4 of Circular 96/2015/TT-BTC) mentioned above.
- Expenses for supporting organizations, social organizations, and charitable activities that do not meet the conditions specified in Article 4 of Circular 96/2015/TT-BTC shall not be included in deductible expenses when determining taxable income for corporate income tax.
Accordingly, expenses for sponsorship and support by enterprises in the fields of education, health, and disaster recovery shall be deducted from taxable income for corporate income tax if these expenses are made to the right subjects and have full supporting documents as prescribed by law. These documents include full invoices, legal documents, and other relevant documents provided by the organization or competent authority.
In contrast, expenses for sponsorship, support, or charity activities for organizations and social organizations that do not meet the conditions prescribed by law shall not be deducted from taxable income for corporate income tax. This ensures that corporate charitable and sponsorship activities must be transparent, compliant with regulations and carried out for specific purposes permitted by law to enjoy tax benefits.
2. Legal documents of charitable and humanitarian contributions to determine deductible expenses
When a enterprise makes charitable or humanitarian contributions, it must be or support in accordance with legal regulations, in order for these expenses to be deducted when determining taxable income for corporate income tax, the enterprise needs to provide the following documents:
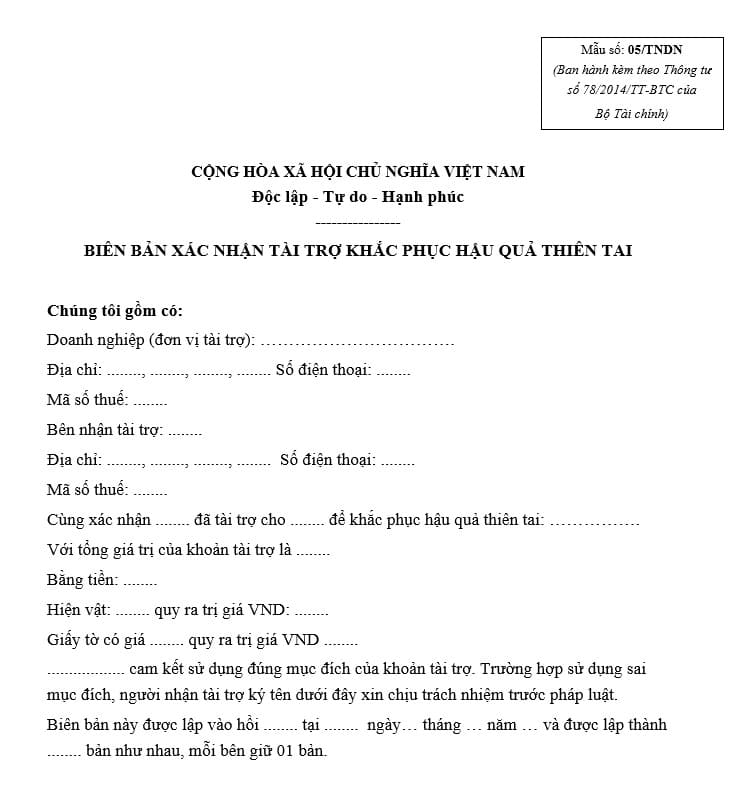
- Minutes confirming the sponsorship: This minute must be signed by the representative of the enterprise (sponsor) and the representative of the organization damaged by natural disasters or the agency or organization with the function of mobilizing sponsorship (the unit receiving the sponsorship). The minute must be prepared according to form No. 05/TNDN issued with Circular No. 78/2014/TT-BTC.
- Documents for purchasing goods: If sponsoring in kind, the enterprise needs to provide invoices and documents related to the purchase of goods that the enterprise uses for sponsorship.
- Documents for payment: If sponsoring in cash, the enterprise needs to provide payment documents, including documents verifying the transfer or payment to the unit receiving the sponsorship.
Having all the above documents will help enterprises prove the legality of the expenditure and ensure that it can be deducted from taxable income.
3. Guidance on accounting for charitable support expenses
According to Article 94 of Circular 200/2014/TT-BTC, accounting for charitable support and sponsorship expenses in Account 811 – Other expenses is necessary to record expenses incurred that are not directly related to the main business activities of the enterprise.
These are expenses that are not deductible when calculating corporate income tax (CIT), and they will be adjusted when settling taxes, leading to an increase in the amount of tax payable. This emphasizes the importance of accurately classifying and accounting for expenses to ensure compliance with the law and avoid legal risks.
Instructions for accounting for charity support costs:
- Accounting for charity support costs in cash:
Debit account 811 – Other expenses
Credit account 111, account 112 – Cash or bank account (if transferred)
- Accounting for charity support in goods:
Debit account 811 – Other expenses (according to the actual value of the item)
Credit account 156 – Inventory (or account 152 – Raw materials, materials)
- Accounting for charity support costs in services:
Debit account 811 – Other expenses (according to the value of free services)
Credit account 338 – Other payables (or account 3381 – Other collections and payments)
Enterprises participating in charity activities, especially supporting flood-hit areas, not only demonstrates social responsibility but also contributes to reducing difficulties for the community. However, in order for this charity expense to be considered a reasonable expense and deductible when calculating corporate income tax, businesses need to strictly comply with legal regulations, including implementing the right objectives and having full verification documents.

